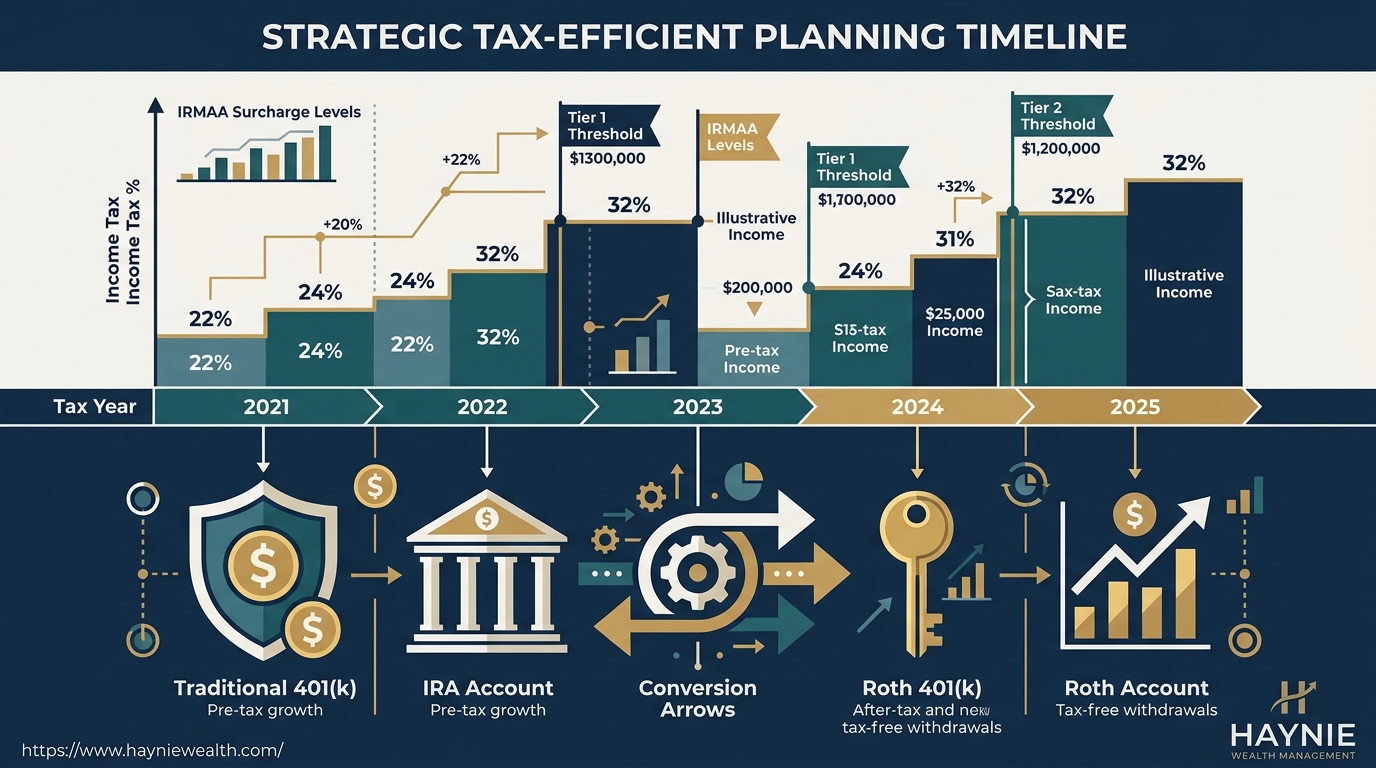
Year-End Roth Conversion Windows: Managing Tax Brackets Across Multiple Years
A Roth conversion is not simply a choice between paying tax now or later. For experienced retirees and high-net-worth professionals, the better question is whether a series of carefully sized...
Read more
The Right Retirement Plan Can Change Everything, But Only If You Have One
The Plans Available to You And What You Can Still Do This YearAs a business owner, planning for retirement is one of the most consequential financial decisions you'll make, not just for your own...
Read more
Trump Accounts: Benefits, Tradeoffs, and Where They Fit
As new savings strategies continue to emerge, Trump Accounts have captured attention as a way to give the next generation a powerful early start on long-term wealth building. Their appeal is simple...
Read more
Make the Most of Your IRA and HSA Contributions Before Tax Day
With tax season fast approaching, now is an ideal moment to review your financial game plan—especially when it comes to maximizing contributions to your IRAs and HSAs. These accounts offer valuable...
Read more
Dividing Retirement Accounts After Divorce: 5 Tax Mistakes to Avoid for a More Secure Retirement
Avoiding Costly Tax Errors When Dividing Retirement Accounts in DivorceDivorce is one of the most financially complex transitions an individual can face. Along with dividing property, real estate,...
Read more
How to Choose the Right Financial Advisor: 5 Steps to Finding Your Best-Fit Advisor
Choosing the right financial advisor is a pivotal decision—one that can influence your retirement strategy, tax efficiency, investment outcomes, and long-term wealth preservation. With today’s...
Read more
What Adults With Student Loans Should Understand About Planning for Retirement
Managing Student Debt While Preparing for the FutureAcross the United States, two financial pressures weigh heavily on many adults: student loans and retirement savings. More than 43 million...
Read more
How to Build an Income Ladder Without Chasing Yield
Maximizing Your Retirement Income Strategy with Secure InvestmentsCreating a stable and predictable retirement income strategy without chasing high-yield, high-risk investments is both achievable...
Read more
Jump-Start Your Financial Health This January: A Practical Guide to Getting Back on Track
January is the perfect time to take a closer look at your finances and set the stage for a more intentional year. One of the most effective places to begin is by reviewing last year’s spending....
Read more
Step-Up in Basis: How Heirs May Reduce Capital Gains
Understanding Step-Up in BasisUnder tax law, the "step-up in basis" rule allows an inheritor to adjust the original value of an inherited asset to its market value at the time of the owner's death....
Read more
The First Five Years of Retirement: Taxes, Withdrawals, and Benefits
Understanding the Early Retirement LandscapeRetirees entering their first five years of retirement often encounter unique financial challenges. From adjusting to new spending patterns to organizing...
Read more
Asset Location 101: Improve After-Tax Returns Across Accounts
Optimize Your After-Tax Returns with Strategic Asset LocationAdvanced asset location strategies can significantly boost after-tax returns by strategically allocating investments across taxable, tax...
Read more
RMD Sequencing: Lower Taxes and Avoid Penalties
As retirees navigate their post-working years, managing Required Minimum Distributions (RMDs) becomes a critical task. Proper sequencing of RMDs can help minimize tax liabilities, manage Medicare...
Read more
Understanding 2026 Tax Brackets and Strategic Planning
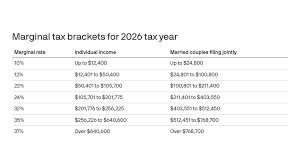
As we look ahead to 2026, major shifts are on the horizon for tax planning. The IRS recently released the official 2026 income tax brackets, reflecting changes implemented under the “One Big...
Read more
Should You Claim at 62, 67, or 70? A Timing Guide
Choosing the Right Age: Maximize Social Security BenefitDeciding when to claim Social Security benefits is a crucial decision that can impact your long-term financial stability. Considering...
Read more
Medigap vs. Medicare Advantage: Costs, Networks, and Tradeoffs
Understanding Your Options:Medigap vs Medicare AdvantageChoosing between Medigap and Medicare Advantage is a critical decision for retirees seeking to optimize their healthcare coverage. While both...
Read more
Don’t Let Outdated Beneficiaries Derail Your Estate Plan
One of the simplest yet most overlooked parts of estate planning is keeping your beneficiary designations up to date. Retirement accounts, insurance policies, and trusts all rely on beneficiary...
Read more
Open Enrollment Checklist for North Houston Retirees
Maximize Your Medicare: An Open Enrollment Checklist for Retirees in North HoustonAs open enrollment approaches, it’s crucial for retirees in North Houston to optimize their Medicare plans. This...
Read more
Fall Into Good Financial Practices For A Strong Year End
As the holiday season approaches, it's easy to feel overwhelmed by the hustle and uncertainty of your financial standing. But fear not! The crisp autumn air offers a perfect chance to hit pause,...
Read more
One Big Beautiful Bill Act: What You Need to Know
Understanding the One Big Beautiful Bill ActThe "One Big, Beautiful Bill" Act (OBBBA) isn't just a political catchphrase—it's a pivotal piece of legislation that brings both permanent and temporary...
Read more
End the Year Strong: 4 Key Financial Moves to Consider
The Clock is Ticking: Take Control of Your FinancesAs the end of the year draws near, it's the perfect moment to seize control of your financial planning. We understand that financial tasks can...
Read more
National Annuity Awareness: Securing Your Future
June Celebrates National Annuity Awareness MonthWith June marking National Annuity Awareness Month, it's a perfect time to explore how annuities could be a pivotal part of your retirement planning....
Read more

Social Security Fairness Act: What Retirees Need to Know
Read more
Timing is Key: Understanding RMDs in a Market Slump
Roth Conversion and TimingWith the market down, some individuals might see the present time as an opportunity to expedite Roth conversions. However, they must remember the sequence: RMDs must be...
Read more

2025 Update: New Rules for Inherited IRAs
Staying informed about retirement account rules is crucial for beneficiaries, particularly as regulations continue to evolve. One area that has caused confusion is the handling of Required Minimum...
Read more

Understanding Risk Tolerance for Smarter Investments
Discovering Your Comfort with Risk: A Crucial Investment StepWhen it comes to managing investments, knowing your risk tolerance is not just beneficial—it's essential. Balancing the opportunity for...
Read more

Understanding Tax Benefits and Implications of Homeownership
Beyond the pride of owning a home, there are significant financial benefits that come with it, especially during tax season. As a homeowner, navigating these benefits can feel overwhelming due to...
Read more
Exploring Charitable Giving Options for Maximum Impact
Read more
Key Considerations for Roth Conversions
Understanding Roth Conversions: Important ConsiderationsWhen it comes to retirement planning, one of the strategies that often pops up is the Roth conversion. The decision to convert traditional...
Read more
Navigating Missed RMDs: A Step-By-Step Approach
Read more
Understanding Risk Tolerance for Smarter Investments
Discovering Your Comfort Zone: Navigating Risk Tolerance Investing can be a thrilling yet daunting endeavor, as balancing opportunities with their potential losses is inherently challenging. Our...
Read more
IRA New Year's Resolutions for a Financially Secure Future
As the new year unfolds, it's the perfect time to revisit our financial goals and commitments. A crucial aspect of financial planning involves managing your Individual Retirement Accounts (IRA)...
Read more
View more